Uthrive: Rewards & Cashback

Screenshots
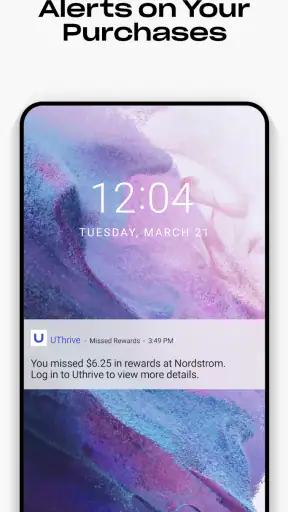
Details
- Rating
- 87.00 reviews
- Version
- 2.3.7
- Developer
- Uthrive.club
Analysis by Norviv
I approached Uthrive: Rewards & Cashback as a practical finance app rather than a game of chasing every possible promotion. Its purpose is straightforward: help me notice cashback opportunities, activate eligible offers, and make better use of the credit cards I already have. That sounds simple, but the real value depends on whether the app fits naturally into my shopping routine instead of becoming another place I have to remember to check.
After using it as a rewards companion, my view is that it works best for people who regularly pay with credit cards and are willing to spend a little time organizing their offers. It is less compelling for someone who wants completely automatic savings with no account setup, no offer review, and no need to think about which card to use. The app is free to install, carries an Everyone age rating, and comes from Uthrive.club, but optional in-app purchases range from ten cents to nearly seventy dollars per item, so I would still pay attention to any purchase screen.
How the app feels in everyday use
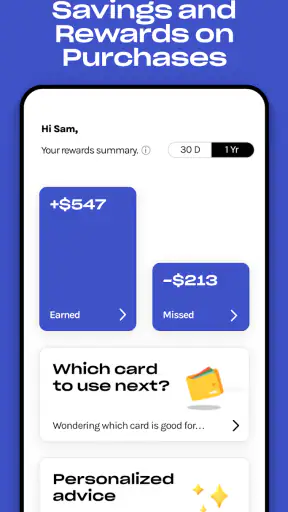
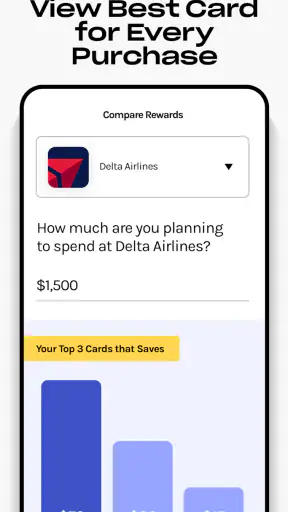
The first thing I noticed is that the experience is built around reducing the effort involved in finding rewards. Instead of manually checking every card issuer, retailer, or deal page, I can use the app as a central place to look for relevant cashback opportunities. Its main promise is not that it changes how I spend, but that it can make existing spending more rewarding when I choose the right offer before paying.
That distinction matters. I would not treat the app as a reason to buy something I do not need. Cashback only helps when the purchase was already planned and the conditions are clear. A discount can easily become expensive if it encourages an unnecessary order, or if I use a card that carries interest. My preferred approach is to check the app before routine purchases, activate only offers that match something I was already going to buy, and then keep my normal payment habits.
The interface feels most useful when I have a specific shopping intention. For example, if I am preparing for a grocery run, replacing a household item, or planning an online order, I can open the app first and see whether a suitable offer is available. That is more efficient than browsing without a purpose. The app becomes a filter for decisions rather than a stream of promotions that controls my spending.
Its store listing presents the possibility of unlocking more than four hundred dollars in cashback, but I would read that as an upper promotional opportunity rather than a personal guarantee. The amount any individual earns depends on available offers, eligible cards, purchase timing, and spending patterns. In my experience, the strongest benefit is the cumulative effect of catching rewards I might otherwise overlook, not a sudden windfall.
Speed expectations and the value of quick checks
For this type of finance app, perceived speed is less about flashy animation and more about how quickly I can move from opening the app to understanding what action is available. Uthrive feels most effective when I use it in short sessions: check an offer, decide whether it fits, activate it if appropriate, and close the app. That workflow keeps the app from becoming a time-consuming part of shopping.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would not open it expecting every reward decision to be resolved instantly. Offers need to be read carefully, especially when several cards or merchants are involved. The fastest experience comes from knowing what I am looking for before launching the app. A vague browsing session can take longer because I am comparing possibilities rather than completing a clear task.
A useful habit is to review offers at the beginning of the week, then perform a quick check before a larger purchase. This avoids repeatedly scanning the same material while still giving me a chance to catch something relevant. I also prefer activating an offer before I reach checkout, because trying to make a rewards decision at the last moment adds unnecessary pressure and makes mistakes more likely.
The app’s current version is 2.3.7, which suggests that the product has continued receiving updates since its release on November 4, 2021. I would still judge speed in context: an app that handles financial offers needs to prioritize clarity and correct status information over aggressive visual transitions. If a screen takes a moment to load but makes the offer conditions easier to understand, that is a reasonable trade-off for me.
What happens during heavier use
Light use is the natural fit here, but heavier sessions can happen when I am comparing several cards, reviewing many merchants, or planning a larger shopping trip. In those moments, the app’s usefulness depends on organization. I do not want to scroll through unrelated possibilities when I already know the category or retailer I need. The more deliberate my search, the less demanding the session feels.
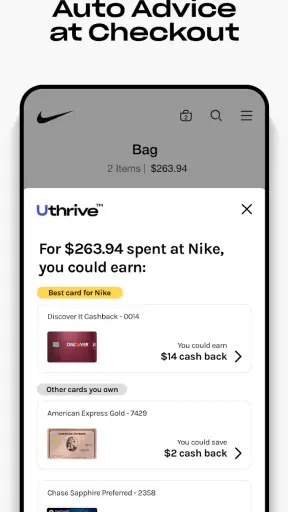
One non-obvious advantage is that I can use the app as a pre-purchase checklist rather than a post-purchase disappointment. Before paying, I can confirm that the offer is relevant, that I am using the intended card, and that I have completed whatever activation step is required. This small routine is more valuable than simply opening the app after a transaction and discovering that I missed the opportunity.
Another practical trade-off is that maximizing rewards can make shopping slower. If I compare every possible card for every small purchase, the time and mental effort may outweigh the benefit. I reserve detailed comparisons for planned or higher-value spending and use a simpler default for everyday transactions. That keeps the app helpful without allowing rewards optimization to take over my routine.
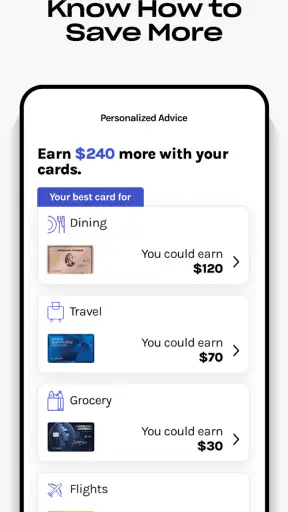
People who monitor several credit cards may get more from Uthrive than someone with one simple card. With multiple accounts, the app can serve as a reminder to consider which payment method makes sense. However, more cards also mean more conditions to understand. I would never assume that a visible offer applies automatically to every card in my wallet; I would verify the relevant details before relying on it.
Reliability, offer status, and personal records
Reliability is especially important in a cashback app because the result may not be obvious at the moment of purchase. I found it sensible to treat the app as a planning and activation tool, not as the only record of my finances. I keep receipts, watch my card statements, and note important purchases until the expected reward has appeared. That is good financial housekeeping regardless of which rewards service I use.
The app is rated 4.2 on average from around 281 ratings, with roughly 87 written reviews. That gives me a generally positive impression from other users, although it is not a substitute for checking whether the workflow suits my own cards and shopping habits. A rewards app can be useful to one person and frustrating to another simply because their merchants, payment methods, or expectations differ.
I also appreciate the importance of separating offer discovery from financial certainty. Seeing a promotion does not mean I should count the money immediately. I would wait until the purchase is complete and the reward is reflected through the expected process before treating it as savings. This cautious approach protects me from building a budget around cashback that has not yet arrived.
When something does not seem right, I would first check the offer wording, activation status, purchase date, merchant details, and card used. Those are the practical points most likely to explain a missed reward. If the information still does not line up, I would use the relevant support route rather than making another purchase to test the system. The app is most reliable as part of a careful process, not as a replacement for reading terms.
Device limits and resource expectations
Uthrive supports Android devices running version 6.0 or later, which makes it accessible to people using older compatible phones as well as newer models. The broad compatibility is useful for a finance tool because I do not need a premium handset just to check an offer. Still, older hardware can make any modern app feel less responsive when several screens are open or when the operating system is heavily burdened by other tasks.
My practical advice is to keep enough free storage and avoid judging the app during a moment when the entire phone is struggling. Finance apps are better evaluated during normal use: opening the app, reviewing an offer, activating it, and returning to the shop or browser. If the phone is already slow, the bottleneck may not be the rewards app itself.
I would also avoid relying on it as an emergency tool at the checkout. A stable routine is to check offers before leaving home or before beginning an online order. That reduces dependence on a busy mobile connection, prevents rushed decisions, and gives me time to read the conditions. The app’s role is to improve preparation, not to create a last-second workaround.
Resource demands matter less here than they would in a video-heavy or constantly active application. My use is naturally occasional, so I would not expect it to be running continuously. I prefer opening it when needed, completing the reward task, and closing it. That pattern is also healthier for attention: I am checking for a concrete benefit instead of endlessly browsing promotions.
Who will get the most from it
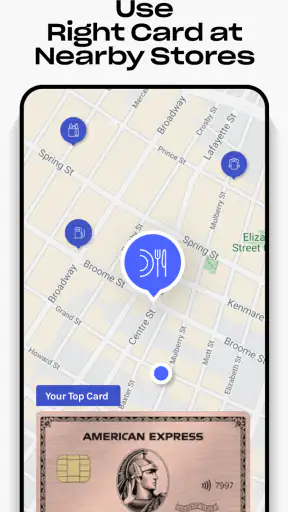
This app is a good match for a person who already uses credit cards responsibly, shops with participating merchants, and wants a central place to look for cashback opportunities. It can be particularly useful for planned purchases, recurring household spending, and people who have several cards but do not always remember which one may be appropriate.
A realistic example would be a weekend household purchase. Before ordering, I open Uthrive, look for a relevant offer, activate it if the conditions fit, and then pay with the intended card. I save the receipt and check the account later. The process takes a little preparation, but it can turn a routine purchase into an opportunity I would otherwise have missed.
The app is less suitable for someone who carries a credit-card balance, buys things mainly because a reward is advertised, or dislikes reading offer conditions. Cashback cannot compensate for interest charges, late fees, or unnecessary spending. It is also not the best choice for a person who wants a simple bank-issued rewards program with no additional app to manage. In that case, the card provider’s own tools may feel more direct.
Compared with ordinary card apps, Uthrive is more focused on bringing reward opportunities together and encouraging active offer use. A bank app may be better for statements, payments, balances, and account security, while this app is better viewed as a companion for finding and activating savings. Compared with coupon sites, its credit-card focus is more relevant when the reward depends on payment method, but a general coupon service may be preferable when I only want a straightforward discount code.
Costs, expectations, and sensible boundaries
The app itself is free to download, which makes trying the basic experience relatively low risk. However, the presence of optional purchases means I would not assume every part of the experience is cost-free. I would read each purchase screen carefully, confirm whether an item is genuinely useful to me, and avoid paying for a promise of savings that I cannot realistically use.
The Everyone rating makes it broadly approachable, but age suitability is not the same as financial suitability. Younger users and anyone new to credit cards should focus first on responsible payment habits. The best reward is still avoiding interest and buying only what the budget allows. I would recommend using the app as an educational prompt to compare choices, not as permission to spend more.
One of my strongest tips is to calculate the effort involved. If an offer saves a small amount but requires a complicated purchase decision, several account checks, or a change from a familiar card, it may not be worth pursuing. For larger planned purchases, the calculation changes. The app becomes more useful when the possible reward is meaningful and the conditions are easy to satisfy.
My performance verdict
From a performance perspective, Uthrive: Rewards & Cashback is best understood as a lightweight, occasional finance companion. Its perceived speed is strongest during focused checks, its heavier-use moments are manageable when I narrow the search, and its reliability depends partly on my own habit of confirming activation and keeping purchase records. I would not use it as a substitute for a bank app, a statement archive, or personal budgeting discipline.
The developer, Uthrive.club, has built an app with a clear everyday purpose: help users make more deliberate use of card rewards. The product has passed the early stage of simply appearing in an app store, with over ten thousand installs, but I still think individual expectations matter more than popularity. Someone with frequent eligible spending may find it worthwhile, while someone who rarely uses credit cards may see little reason to add another financial tool.
My final recommendation is cautious but positive. I would install it if I already had planned purchases, multiple cards, or a habit of missing available cashback offers. I would begin with free features, test the activation workflow on ordinary spending, and keep my own records before trusting the process for a major purchase. The key is to use rewards as a by-product of sensible spending, never as the reason to spend.
Used that way, Uthrive can make reward hunting faster and more organized without demanding constant attention. It is not magic, and it does not remove the need to read conditions or monitor accounts, but it offers a practical middle ground between doing all the research manually and relying only on whatever a single card issuer happens to display. For the right shopper, that balance makes it worth trying.
Frequently Asked Questions
01What is Uthrive: Rewards & Cashback?
Uthrive: Rewards & Cashback is a shopping rewards app designed to help users earn cashback, discounts, or other incentives when they shop through participating brands and offers. After installing the app, users can browse available deals, review the reward conditions, and access retailers through the platform. The exact reward amount and eligible stores may vary depending on location and current promotions.
02How do I earn cashback with Uthrive?
To earn cashback, you generally need to select an eligible offer in Uthrive, follow the app’s instructions, and complete your purchase through the required link or partner process. Some offers may require activating a deal before shopping, using a specific payment method, or meeting a minimum purchase amount. Always read the terms carefully, because purchases made outside the tracked process may not qualify.
03How and when can I receive my Uthrive rewards?
Reward processing times and redemption methods can depend on the offer, retailer, and account status. In many cashback services, a transaction first appears as pending while the purchase is verified, then becomes available after returns, cancellations, or refunds are excluded. Before downloading, check the app’s current withdrawal options, minimum payout threshold, supported payment services, and any expiration rules that may apply.
04Is Uthrive: Rewards & Cashback free to download and use?
The app may be free to download, but users should still review its terms before signing up or making purchases. Cashback platforms can include offer-specific restrictions, excluded products, transaction requirements, or optional features that affect how rewards are earned. You should also verify whether the app is available in your country and whether participating retailers support your preferred currency or payment method.
05What should I know about privacy and account requirements?
Uthrive may require an account and certain personal or transaction information to track purchases, confirm eligibility, and deliver rewards. Before creating a profile, review the app’s privacy policy, permissions, data-sharing practices, and account deletion process. Avoid providing unnecessary information, and make sure notifications, location access, or email permissions are enabled only when they are genuinely needed for the offers you plan to use.


